What Is a Personal Loan and How Does It Work in Malaysia?
By LajuCreditPublished: 9 min read
A personal loan can provide access to funds for different personal financial needs, from handling an unexpected expense to covering a planned cost. However, borrowing also creates a financial commitment that needs to be repaid according to agreed terms.
Before applying, it helps to understand how personal loans work, how repayments are calculated and what lenders may consider when assessing an application.
If you are currently comparing a personal loan Malaysia option, understanding these basics can help you look beyond the amount offered and evaluate the overall financial commitment.
This guide explains how a personal loan works in Malaysia, what you may need to prepare and what to check before submitting an application.
What Is a Personal Loan?
A personal loan is a type of financing where an individual borrows an agreed amount from a lender and repays it according to the terms of the financing agreement.
Depending on the product, repayments are generally made over an agreed period and may include interest or profit charges together with applicable fees.
Personal financing may be considered for different needs, such as unexpected expenses, home-related costs, education expenses or other personal financial commitments.
However, money received through a loan is not additional income. It needs to be repaid.
That is why the amount you can borrow should not be the only consideration. The amount you can comfortably repay is equally important.
How Does a Personal Loan Work in Malaysia?
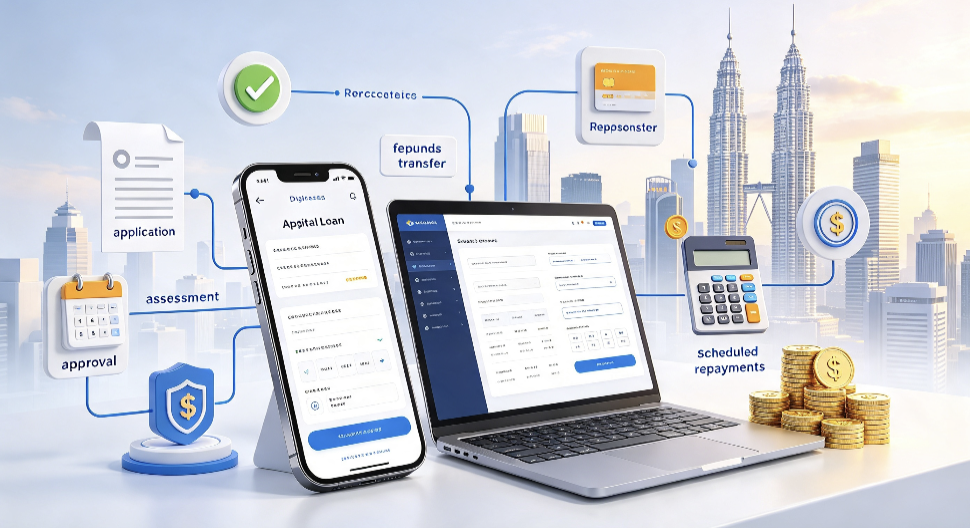
The exact process varies between lenders and financing products, but it generally involves several stages.
First, you submit an application with the information requested by the lender. Depending on the provider, this may include personal, employment, income and financial information.
The lender then assesses the application according to its eligibility and credit assessment requirements.
If the application is approved, you should be provided with the applicable financing terms. These may include the approved amount, interest or profit rate, repayment period, monthly repayment and relevant charges.
Once the funds are disbursed, repayments need to be made according to the agreed schedule.
An important point to remember is that submitting an application does not guarantee approval. Different lenders use different eligibility and assessment criteria.
Secured vs Unsecured Personal Loans
Personal financing can generally be structured as secured or unsecured financing.
A secured loan involves an asset or another form of security being provided against the financing.
An unsecured personal loan, on the other hand, generally does not require an asset to be pledged as collateral. The lender instead assesses the applicant according to its lending criteria.
These criteria may include income, existing financial commitments, credit information and other relevant factors.
Because the structure and requirements can vary between products, always review the actual terms of the financing rather than assuming all personal loans work in the same way.
How Does an Online Personal Loan Application Work?
Many financing applications can now be started or completed online.
When applying for a personal loan online in Malaysia, you may be able to provide the required information and supporting documents through a website or digital platform.
However, an online application does not remove the lender's assessment process.
The lender may still need to verify your identity, assess your income and existing commitments, review relevant credit information and determine whether you meet its requirements.
Therefore, terms such as online personal loan Malaysia or loan online Malaysia describe the application channel. They should not be interpreted as guaranteed approval.
Digital applications can make the process more convenient, but the financing terms still matter.
What Determines Whether a Personal Loan Is Approved?
There is no single factor that determines whether every personal loan application will be approved.
Different lenders have their own assessment policies.
Depending on the product, factors considered may include your income, employment information, existing financial commitments, credit information and ability to meet the proposed repayments.
Your application may also be assessed against the lender's minimum eligibility requirements.
This means two applicants requesting the same amount may not necessarily receive the same outcome.
It also means meeting a lender's basic eligibility requirements does not automatically guarantee approval.
Does Your Credit History Matter?
Credit information may form part of a lender's assessment.
In Malaysia, CCRIS contains financing and repayment information reported by participating financial institutions. Bank Negara Malaysia explains that CCRIS itself does not blacklist borrowers or decide whether a financing application should be approved.
Instead, financial institutions may use the information alongside other factors when conducting their own assessment.
Consumers can also review their own CCRIS information through Bank Negara Malaysia's eCCRIS service.
Knowing your existing financial commitments can be useful before taking on another repayment obligation.
What Should You Check Before Taking a Personal Loan?
Comparing personal loans should involve more than looking at the maximum amount available.
Several elements can affect the overall cost and affordability of the financing.
Interest or Profit Rate
Understand the rate applicable to the financing and how it affects the amount you will eventually repay.
Do not rely only on a headline or promotional rate.
Look at the information provided for the actual product and understand the cost of borrowing before agreeing to the financing.
Monthly Repayment
Consider whether the expected monthly repayment can realistically fit into your budget.
Your existing expenses may include housing, transportation, food, utilities, insurance and other debt repayments.
Adding another monthly commitment without considering these expenses could put pressure on your finances.
Repayment Period
Check how long you will need to make repayments.
A longer repayment period can affect the size of each instalment, but it may also change the overall amount paid throughout the financing period.
For this reason, compare both the monthly commitment and total repayment rather than focusing on one number.
Fees and Charges
Check whether fees, charges or penalties apply and under what circumstances.
Understanding these costs before accepting an offer can help you avoid surprises later.
Total Repayment
One of the most useful figures to understand is how much you are expected to repay in total.
For example, receiving RM5,000 does not necessarily mean your total repayment will also be RM5,000.
Interest or profit and applicable charges can increase the total amount payable.
How Much Should You Borrow?
The maximum amount available to you is not necessarily the amount you should borrow.
A more practical approach is to calculate the amount you actually need.
Suppose you have an unexpected RM2,500 expense. If you qualify for a larger amount, that does not automatically mean taking the maximum available financing is the right choice.
Borrowing more generally means taking on a larger financial obligation.
Start with the financial need, then consider how the expected repayment would fit into your existing monthly budget.
This helps shift the decision from:
“How much can I get?”
to:
“How much do I actually need and how much can I comfortably repay?”
Can You Apply for a Personal Loan Online in Malaysia?
Depending on the provider, yes.
An online loan Malaysia application may allow you to complete different stages of the process digitally, including submitting information and supporting documents.
Before submitting personal information, however, check who you are dealing with.
Understand the financing provider, the product being offered, how your information will be used and the terms that apply if the application is approved.
Online convenience should complement proper financial checks rather than replace them.
Does a Fast Online Application Mean Fast Approval?
Not necessarily.
Someone facing an urgent expense may naturally search for a fast loan online Malaysia option, but a quick application process and a financing approval are two different things.
A digital form might take only a short time to complete, while the provider may still need to assess the application before making a decision.
Be careful with claims that imply every applicant will receive guaranteed or instant approval.
Instead of judging a financing option only by speed, consider the repayment amount, financing period, cost, applicable charges and provider.
What Documents May Be Required?
The documents and information required vary between providers.
Depending on the lender and financing product, you may be asked for information that helps verify your identity, income, employment or existing financial situation.
Providing complete and accurate information can help the lender assess the application.
However, you should also be careful when sharing sensitive personal documents online.
Confirm that you are dealing with the intended provider and understand why the requested information is needed before submitting it.
What Happens After You Submit an Application?
After an application is submitted, the lender may verify the information provided and conduct its assessment.
The outcome may be an approval, rejection or request for additional information.
If financing is offered, review the proposed terms carefully before accepting.
Check the approved amount, repayment period, monthly commitment, interest or profit rate, applicable fees and total repayment.
Do not assume the terms offered will necessarily be identical to the amount or conditions you initially expected when submitting the application.
Personal Loan vs Other Financing Options
A personal loan is only one type of financing.
Depending on the purpose of the expense, consumers may also encounter credit cards, hire-purchase financing, home financing and other credit products.
Each product has its own structure, costs, repayment method and eligibility requirements.
The most suitable type of financing depends on what the money is needed for, the cost involved and whether the repayment commitment fits your financial situation.
For this reason, avoid choosing a financing product solely because it appears easier or faster to obtain.
Preparing to Apply for a Personal Loan
Once you understand how personal loans work, the next step is preparing for the application.
Before you apply for a personal loan in Malaysia, consider checking your income, existing financial commitments, required documents and the amount you actually need.
Our guide on how to apply for a personal loan in Malaysia explains the application process, common information you may need to prepare and what to check before submitting your application.
This is particularly useful if you are moving from researching personal loans to actually considering an application.
Make an Informed Decision Before Applying
Understanding how a personal loan works can make it easier to compare financing options based on more than just the amount offered.
Consider the cost of borrowing, monthly repayment, repayment period, applicable charges and your existing financial commitments.
If you want a broader overview of available considerations, read our personal loan Malaysia guide.
If you are exploring financing through LajuCredit, review the available information, eligibility requirements and applicable terms before making a decision.
A personal loan can help address a financial need, but it also creates a repayment commitment. Borrow based on what you need and what you can reasonably afford to repay.
Your amount, period and full costs are shown after you log in — before you confirm anything.