Licensed Moneylender vs Ah Long: What Is the Difference?
By LajuCreditPublished: 8 min read
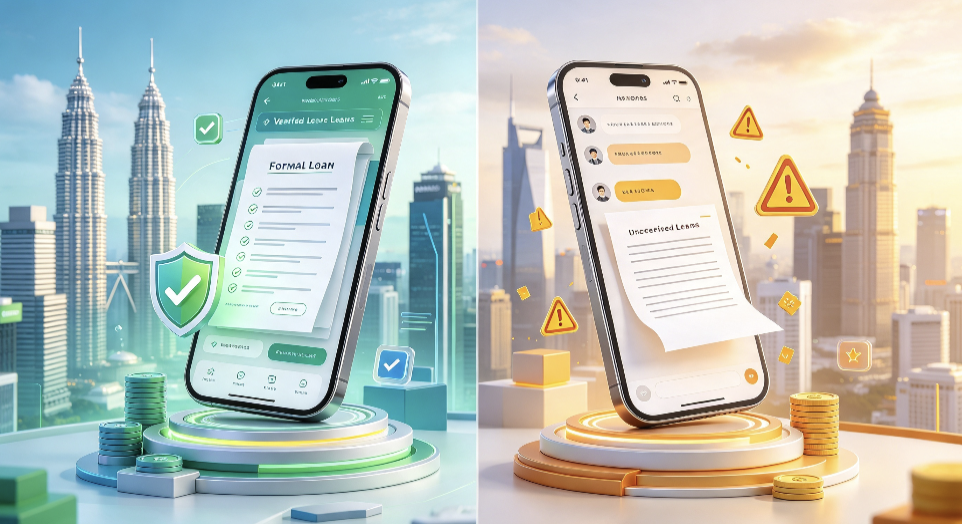
When someone needs money urgently, terms such as money loan, licensed loan and Ah Long may appear in their search. Although all involve borrowing money, licensed moneylenders and Ah Long are not the same thing.
The main differences lie in licence status, the rules that must be followed, loan agreements, interest rates, repayment collection methods and the protections available to borrowers.
In Malaysia, licensed moneylenders, or Kredit Komuniti, are regulated by the Ministry of Housing and Local Government (KPKT) under the Moneylenders Act 1951 [Act 400]. KPKT describes Ah Long as unlicensed moneylenders.
That is why it is important to understand the difference and conduct checks before making any application.
What Is a Licensed Moneylender?
A licensed moneylender loan refers to a loan offered by a moneylender that holds a valid licence to conduct lending activities.
In the KPKT context, the licensed moneylending industry is also known as Kredit Komuniti. The Community Credit Control Division regulates the relevant activities and ensures that only eligible credit providers are licensed.
Holding a licence means that the moneylender must operate under the Moneylenders Act 1951 and the related regulations.
However, licensed status does not mean that every loan is necessarily suitable for every individual. Borrowers must still read the agreement, understand the cost of the loan and assess their own ability to repay.
What Is Meant by Ah Long?
The term Ah Long is generally used to refer to an unlicensed moneylender.
KPKT distinguishes licensed Kredit Komuniti companies from Ah Long, which do not hold a KPKT licence.
This is an important distinction.
Someone who offers money quickly, communicates through WhatsApp or advertises online is not necessarily a licensed moneylender. The application method or the speed of obtaining money does not determine a party’s licence status.
That is why borrowers should not rely solely on advertisements or claims made by the party offering the loan.
Differences Between Licensed Moneylenders and Ah Long
Several important differences can help consumers understand how a licensed moneylender differs from an unlicensed moneylender.
1. Licence and Regulatory Status
The most basic difference is licence status.
Licensed moneylenders are subject to the Moneylenders Act 1951 and the related regulations, while Ah Long operate without a KPKT licence.
Do not simply accept a claim that a company is “licensed”.
Consumers can check through the i-KrediKom app. According to KPKT, the app lets the public search for licensed Kredit Komuniti companies in Peninsular Malaysia and obtain information about borrowers’ rights and offences under the Act and related regulations.
For more detailed steps, read the guide on how to check a KPKT-licensed moneylender before applying.
2. Loan Agreement
Licensed loans have specific requirements relating to the loan agreement.
KPKT’s guide for prospective borrowers states that a Schedule J agreement is used for unsecured loans, while Schedule K is used for secured loans.
KPKT also explains that borrowers should not sign a blank agreement form and are entitled to receive one copy of the agreement free of charge.
By contrast, KPKT materials about Kredit Komuniti and Ah Long state that an unlicensed moneylender’s agreement may be based on its own terms and may take place without the prescribed written agreement.
Therefore, do not assume that an official-looking document necessarily proves that a loan is licensed. The lender’s status must still be checked.
3. Interest Rates
Interest rates are another important difference.
According to KPKT guidance, interest rates for licensed moneylenders must not exceed:
- 12% a year for secured loans; and
- 18% a year for unsecured loans.
KPKT also distinguishes this from Ah Long, which are not subject to the same rate structure and may impose rates that change according to their own wishes.
Before agreeing to a loan, do not look only at the amount you will receive.
Also check the interest rate, total repayment, repayment period and penalties for late payment.
4. Repayment Collection
The way a debt is collected also differs.
According to KPKT information, a licensed moneylender or its representative is not permitted to visit a borrower’s home, office or another place outside the approved business operating address to collect instalments. Harassment or threats against a borrower or their family are also offences under Act 400.
In KPKT comparison materials, debt claims by licensed Kredit Komuniti providers are described as proceeding through civil channels, unlike the violent methods associated with unlicensed moneylenders.
If someone threatens you or your family to obtain payment, do not treat that action as normal simply because you owe money.
5. Borrower Rights
Dealing with a licensed moneylender does not mean a borrower loses all rights after signing an agreement.
Among the matters explained by KPKT are the right to receive a copy of the agreement and a receipt for every repayment. Borrowers may also request an account statement through the prescribed process.
That is why you should keep loan documents, payment records, receipts and copies of relevant communications.
Those documents help you understand the outstanding balance and provide a record if a dispute occurs.
6. Business and Advertisement Information
Another point to examine is the information in an advertisement.
KPKT states that licensed moneylender advertisements must include certain information, including the licence number and validation date, advertising permit number, the moneylender’s name, address and phone number, and the interest rate offered.
Therefore, be careful with advertisements that use only phrases such as “instant loan”, “fast cash” or “confirmed approval” alongside one phone number without providing information that can be checked.
An attractive advertisement is not proof of licence status.
Is an Online Licensed Loan the Same as Ah Long?
Not necessarily.
The fact that a loan is offered online does not by itself determine whether it is licensed.
Therefore, when searching for an online licensed moneylender or an online loan in Malaysia, the main thing to check is who is actually offering the loan.
Do not draw a conclusion based only on the design of the website or app, or the way the provider communicates with you.
If a party claims to offer licensed loans, check the company identity and licence status through an official channel first.
How to Identify a Licensed Moneylender
The safer approach is to conduct your own check.
KPKT provides i-KrediKom, which lets the public search for licensed Kredit Komuniti companies in Peninsular Malaysia.
Licence information described by KPKT includes the name of the individual or company, registered address, approved operating address, licence number and licence start and expiry dates.
Compare that information with the party communicating with you.
If the name, address or other information does not match, do not proceed with a payment or provide sensitive documents before conducting further checks.
Warning Signs to Look Out For
Several signs should make you more cautious before continuing an application.
For example, the company information is unclear, the licence status cannot be verified, the repayment terms keep changing or you are asked to sign an incomplete document.
Also be careful if someone uses the name of a licensed company but the contact details or account being used cannot be matched to the information you checked.
Do not rush simply because the offer has a short time limit.
If you have doubts, stop the process and conduct checks first.
What Should You Do Before Applying for a Loan?
Before applying for a licensed personal loan or any form of money loan, look beyond the amount you can receive.
Ask several basic questions:
Does the moneylender hold a valid licence? What is the interest rate? What is the total amount to be repaid? How long is the repayment period? What is the penalty for late payment? Do you understand every term in the agreement?
KPKT itself recommends that prospective borrowers make sure the licence remains valid and check the interest rate, monthly repayment amount, loan term and applicable penalties.
After that, assess your own financial capacity.
Even a legitimate loan remains a financial commitment that must be repaid.
Check Before Making a Decision
The difference between licensed moneylenders and Ah Long is not merely a matter of names.
Licensed moneylenders operate within a specific legal and regulatory framework, while unlicensed moneylenders do not have that licence status.
That is why you should not assess a loan only by the speed of the process, the amount offered or the appearance of a website.
Check who the moneylender is, confirm the licence status, understand the agreement and calculate the total repayment before making a decision.
If you are just starting to compare options, LajuCredit’s guide to licensed moneylenders can help you understand the basics before proceeding with an application.
If you have already found a moneylender but are unsure about its status, use the guide on how to check a KPKT-licensed moneylender to learn what information to examine first.
Your amount, period and full costs are shown after you log in — before you confirm anything.